Your first home

 in North Atlanta, without the guesswork.

Book a Buyer Strategy Call
Explore the Guide
Path & Post Tee Shirt
Find-Your-Path-text

You have already read half the internet. You know the terms, you have the tabs open, and you still can't tell which advice is actually written for your situation. This is the page that answers that, and a real guide you can talk to when you want a straight answer.

770-720-4663

A first home is a life change not a transaction.

When you buy a house, you’re choosing the street you’ll drive home to every night, the school district down the road, and the commute you’ll be making for years. Most importantly, you’re locking in a monthly payment you actually have to live with while the rest of life keeps happening.

That’s why scrolling real estate sites usually leaves people feeling stuck. The internet gives you broad, generic advice, but your life isn't generic. Your income, your credit score, your timeline, whether family is pitching in, and those three specific neighborhoods you can’t stop looking at are entirely unique to you. A great agent understands that. Their job isn't just to show houses. They're here to tailor a plan to you.

Since 2013, Path & Post has helped thousands of families across North Atlanta close on their homes, many of them for the very first time. And if there’s one thing we’ve learned, it’s this: the buyers who walk up to the closing table feeling calm and confident are always the ones who knew exactly what to expect at every single step along the path.

Homebuying Journey

What actually happens, in order.

Custom Search & Private Showings

We provide early access to Coming Soon properties, private access to off-market properties, and preferred touring for Active MLS Properties.

Finance Plan & Lender Options

A pre-approval is the gold standard to determine down payment, monthly payments, and closing costs. Whether you are paying cash or getting a loan, we help find solutions and options from trusted lenders.

Offer & Negotiations

We use a combination of strategy & data to win for you. Be prepared to provide 1% to 3% of the sales price as Earnest Money.

Due Diligence & Negotiations #2

We guide & protect with inspection advice and vendor recommendations. We may also negotiate adjustments to contract terms based on findings. Common expenses: inspections, the appraisal, and your homeowners insurance policy (shop for the best coverage and terms).

CONTINGENCIES & CLOSING PREP

Once financing is approved, appraisal is completed, and contingencies removed, we set up a closing time, collect utility info, review closing statement, and confirm final amount you should wire to closing attorney.

Walk-Thru, Closing, & Beyond

A final walk-through to confirm details are as agreed upon. Sign documents at closing. Celebrate! We provide concierge treatment to you as our client for life!

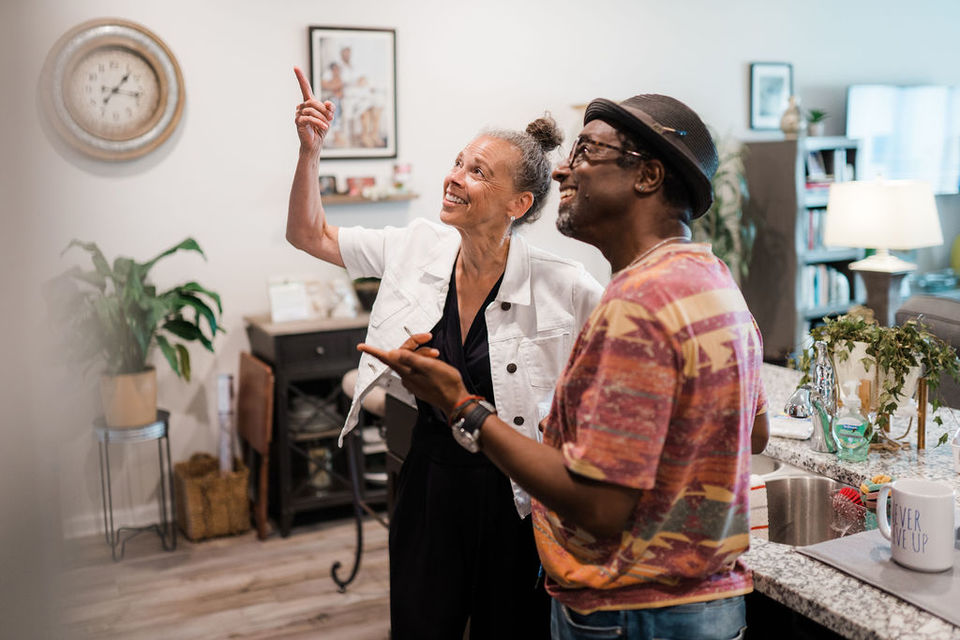
The inspection is not a test

Every home has an inspection report, and every report has a list. New buyers open it, see forty items, and panic. The skill is reading it: which findings are safety and structure, which are normal wear, and which are worth a repair request or a credit at closing.

The same goes for the seller's disclosure. It is a document that rewards a careful reader, and careful reading is the one thing first-time buyers tend to do naturally. Point that instinct in the right direction and it becomes an advantage.
The inspection is not a test

Does this sound like you?

  • You've run the rent-vs-buy math more than once and still aren't sure.
  • You're tired of paying your landlord's mortgage and wondering when it's your turn.
  • You have no idea how much cash you actually need at the closing table.
  • You've saved dozens of homes online but can't tell which ones fit your budget.
  • You want someone to explain each step before it happens, not after.
Relax

We are

Guides Along Your Journey

What Payment

can you manage?

Use our Mortgage Calculator to estimate payments. You can input a different home price, down payment, loan term and interest rate to see how your monthly payment changes.

Custom

PROPERTY SEARCH

Stop searching and start finding! Sometimes the ideal property is not on the market. Submit your custom wants and needs for us to search off-market opportunities for you.

Pre-Qualification vs

Pre-Approval

A real pre-approval means they pulled credit, checked your debt-to-income, and put their commitment on paper. Pre-Approval is the letter that makes a seller take your offer seriously.

What is your

Buying Power?

Lenders qualify you on payment, not price. At the same monthly payment, a one-point drop in interest rate supports a loan roughly 10% larger, so your rate matters as much as the list price.

Frequently Asked Questions & Answers

Buying a first home asks more of you than it did a generation ago. The buyers who close calmly are the ones who knew each step before they reached it. Here are the questions we hear most.

Book a Buyer Strategy Call

Compare the two over the years you plan to stay, not month to month. Buying usually wins the longer you stay, because closing costs spread over more years and every payment builds equity. If you might move within two years, renting can be the smarter call, and we'll tell you so.

Read more: Rent vs Own: How to Decide

Often less than people think. Some conventional programs for first-time buyers go as low as 3% down, FHA loans as low as 3.5%, and VA and USDA loans can require nothing down for eligible buyers. Gift money from family works on most loan types with a signed gift letter, and Georgia Dream offers down payment assistance to buyers who meet its income limits.

Read more: Mortgage Calculator

No. Lenders look at the whole picture: payment history, debt-to-income, savings and the loan program you choose. Minimum scores vary by program and lender, and FHA loans are built for buyers still rebuilding credit. If your score needs work, a good lender can show you which two or three moves raise it fastest.

Read more: Do I Need Perfect Credit to Buy a Home?

A pre-qualification is an estimate based on what you tell a lender. A pre-approval means the lender pulled your credit, verified your income and assets, and put a commitment on paper. Sellers take an offer seriously when a pre-approval is attached, so get one before you tour.

Read more: Pre-Qualification vs Pre-Approval

Plan for three buckets. Earnest money (usually 1% to 3% of the price) goes in when your offer is accepted and counts toward your purchase at closing. Inspections and the appraisal, a few hundred dollars each, come during due diligence. Closing costs typically run 2% to 5% of the price, and sellers can agree to cover part of them.

Read more: What Buyers Should Expect at Closing

Before we tour homes together, you'll sign a buyer brokerage agreement that spells out what your agent does and how the brokerage is paid. Sellers often cover that fee, either through an offer of compensation or a concession you negotiate in the contract. The agreement also shows what happens when they don't, so you know the number before you see a single house.

Read more: Why Buyers Need a Brokerage Agreement

Finding the right home can take a weekend or a few months, depending on your price point and how specific your list is. Once your offer is accepted, most financed purchases close in 30 to 45 days. Getting pre-approved before you tour is the biggest single thing that shortens the first part.

Read more: A Guide to Real Estate Purchase Contingencies

It will. Every report has a list. Under the standard Georgia REALTORS® contract, inspections happen during a due diligence period you negotiate in the offer, and you can walk away during that window for any reason. Your agent helps you separate safety and structural issues from normal wear, then decide whether to ask for repairs, a lower price or a closing credit.

Read more: 10 Inspections Buyers Should Seriously Consider

Wire fraud targets buyers in the last week before closing, usually with an email that looks like it came from the attorney's office. Before you send a dollar, call the closing attorney at a number you found yourself and confirm the wiring instructions out loud. A last-minute change to those instructions is the red flag.

Read more: Real Estate Scam Alert

File for Georgia's homestead exemption with your county tax assessor. You must own and live in the home on January 1, and the application is due April 1, so if you close after January 1, you'll file the following spring. It's one of the easiest ways to lower your property tax bill, and plenty of first-time owners miss it.

Read more: Property Taxes Explained

The First-Home Library

The articles our guides send first-time buyers most, organized by the step you're on. Start where you are.

Most first-time buyers start with one question: is this the right time for me? These cover the rent-or-buy math, the myths that stall people, and the fears worth naming out loud.

Your contract gives you a window to inspect, ask questions and renegotiate. These explain what to check and how contingencies protect you.

The last week has its own checklist: final numbers, the walk-through, and keeping your wire safe.

Owning starts at closing. File your homestead exemption, understand your tax bill, and watch what your payments build.

Your Next Step

Start Your First-Home Plan

Sit down with a Path & Post guide. We'll map your budget, your timeline and the neighborhoods on your list, then show you exactly what happens next. No pressure and no pitch.

"They were so phenomenal at explaining the entire process from the very fundamentals of home buying all the way until the last signature was signed at closing."
Path & Post client

Rather talk now? Call 770-720-4663.

  • When are you hoping to move?

  • Have you talked to a lender yet?

  • Where should your guide reach you?